Posts

Showing posts with the label required minimum distribution

Marking Time — When Retirement Milestones Become Personal

Image
  There’s something about a birthday that ends in zero that hits differently. And I have one of those this week. I’ve spent more than half my professional life thinking, writing, and talking about retirement — how people get there, how they prepare (or don’t), and what it all means when work finally loosens its grip. And yet, when you hit a milestone like this, “theory” gets very personal very fast. Truthfully, this isn’t what I thought “this” would feel like. Not dread. Not triumph. Just … different. Though lately, I’ve been thinking about it more than I expected. See, it’s not just another candle (you’d have to forewarn the local fire department). It’s a checkpoint. A round number that invites reflection whether you ask for it or not. Sure, it’s just another year. But it’s a whole other category of living. That said — and I’m happy to be able to say this — I don’t “feel” my age. [i]  Or what I thought it would be like to be this age. What I am starting to feel — though only ...
Will the Administration’s Executive Order ‘Work’?

Image
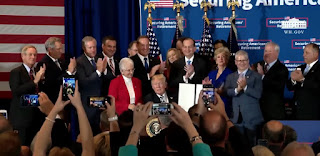
Over the coming weeks, a question that you’re likely to see posed (again and again) about the President’s Executive Order is – “will it work?” “Work” in this case means to expand access to workplace retirement plans, for that is the stated policy of the Trump administration in issuing the order . The answer, of course, will depend in no small part on what emerges as a result. While it’s hard to argue with the underlying principle, and even less with the foundational arguments (“Enhancing workplace retirement plan coverage is critical to ensuring that American workers will be financially prepared to retire” and “Regulatory burdens and complexity can be costly and discourage employers, especially small businesses, from offering workplace retirement plans to their employees”), at this point the order is no more than a directive to the Labor and Treasury Departments to consider and recommend some alternatives. That said, the directives  are reasonably specific – t...

“Drawing” Board?

Image
While drawing boards have been used by engineers and architects for more than two centuries, the phrase “back to the drawing board” is of much more recent origin, coined by the Peter Arno in a cartoon first published in the March 1, 1941 issue of New Yorker magazine.(1) The cartoon features a crashed plane in the background, a parachute in the distance, several military officials and rescue workers rushing to help/investigate—and one remarkably nonchalant individual, walking in the opposite direction with a rolled up document tucked under his arm as he comments, “Well, back to the old drawing board.” For all the much-deserved focus on retirement savings accumulations, a growing amount of attention is now directed to how those already in (and fast-approaching) retirement are actually investing and drawing down those savings. A recent EBRI analysis(2) found that at age 61, only 22.2 percent of households with an individual retirement account (IRA) took a withdrawal from that account...

Means, Tested

Image
Recently the Center for Retirement Research at Boston College released a paper titled “Can Retirees Base Wealth Withdrawals On the IRS’ Required Minimum Distributions?”¹ The answer to that question, according to CRR, is “yes.” A more complete response might be, “yes, or any number of other random withdrawal methodologies.” There are some advantages to a drawdown strategy based on the schedule provided by the Internal Revenue Service (IRS) for required minimum distributions, or RMDs.² First off, and as the CRR paper notes, it’s relatively straightforward. Secondly, it effectively defers initiating withdrawals until age 70-½, which also provides some additional accumulation opportunity. Perhaps most importantly, it helps avoid the stiff penalties the IRS imposes on those who don’t withdraw funds from these accounts at least as rapidly as the RMD schedule provides. The CRR paper cites as an advantage the reality that those drawdowns are based on the portfolio’s current market value, th...

Road "Construction"

Image
The Senate Finance Committee is positioned to pass a highway bill, funded at least in part by changing the tax treatment on retirement accounts. Specifically, the modified chairman’s mark of the proposed Highway Investment, Job Creation and Economic Growth bill would require that age 70-1/2 account distributions be treated, for tax purposes, as distributed within five years of the death of the account holder (unless the beneficiary is the account holder’s age, a child with special needs, or older than 70). Under current law, holders of IRAs and 401(k)-type accounts are required to begin taking taxable distributions from those accounts once they reach age 70-1/2, though if the account holder dies, the taxation of the account is spread over the life of the beneficiary. According to a Senate Finance Committee press release , this particular provision is estimated to raise $4.648 billion over 10 years. The bill’s prospects in the Senate remain unclear, and the Wall Street Journal no...