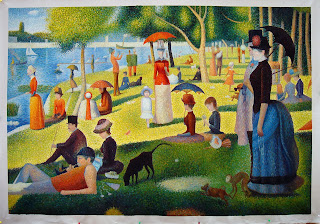Posts

Showing posts with the label individual retirement account

IRA 'Junk' Bunk

Image
   There’s a “new” retirement crisis to fret about — and it involves so-called “junk” IRAs. You may have seen the recent Wall Street Journal’s headline that proclaimed “ Forgotten 401(k) Accounts Are Costing Americans Billions in Lost Investment Gains .” This particular assertion turns out to be another spurred by (yet another) proclamation from an IRA provider (PensionBee), though this one at least doesn’t manufacture quite as ludicrous a compounding of the size and number of those accounts as others [i]  have done. More precisely, the issue they raise is that smaller retirement plan balances can, and often are, legally expunged from the plan of their prior employer into an IRA.   Now, retirement plan professionals know how this works — those who sever (or who are severed from) employment with less than a $1,000 balance will likely have that distributed to them in cash, those with balances above $7,000 [ii]  will generally have the option to leave that bal...

Looking Before You 'Leap'

Image
As new rules about rollover disclosures kick in, a new report highlights an often unacknowledged risk of rollovers—high(er) fees. That’s right—a new report from Pew Trusts seems to have stirred up a new awareness of that issue—all this attention just as PTE 2020-02 brings the  written requirement  of why a rollover is in the best interests of participants into play. That difference shouldn’t come as a surprise to anyone who has ever compared the fees in their 401(k) to an IRA. Most 401(k)s benefit from institutional pricing, and if the menu of available investment options isn’t quite as broad as that in an IRA, they benefit from the selection and monitoring by ERISA fiduciaries. Yes, IRAs are just that— individual  retirement accounts—smaller, generally speaking with more options—and yes, much more likely to be charged retail mutual fund fees—more expensive. In that sense the report—though it’s garnered headlines of...

"Repeat" Performance

Image
A few months back, I was intrigued to catch several episodes of “Cosmos,” an updated version of the classic 1980 Carl Sagan series.  Along with the significantly expanded and enhanced visuals and (to me, anyway, generally annoying) animations, the series recounted the work, travails and accomplishments of Edmond Halley, who, even today, is probably best remembered for the comet whose 75-year cycle he identified and which still, as Halley’s Comet, bears his name. Halley wasn’t the first to see the comet, of course – in fact, it had been recorded by Chinese astronomers as far back as 240 BC, noted subsequently in Babylonian records, and perhaps most famously shortly before the 1066 invasion of England by William the Conqueror (who claimed the comet’s appearance foretold his success).  Halley noted appearances by the comet in 1531, 1607 and 1682, and based on those prior observations – and the application of the work and mathematical formulas of his friend Isaac Newton – pred...

The "Hassle" Factor

Image
Much is made these days of the application of behavioral finance and the implications for plan design, as well as the role of choice architecture in helping workers make “better” (if not more informed) benefit decisions.  Valuable as these insights have been, I think much of human behavior (or lack thereof) in these matters can be more simply explained. What’s at work is a concept a friend of mine described to me more than 20 years ago – something he called “the hassle factor.”  It was a philosophy he routinely applied in many aspects of his personal and professional life.  Simply stated, presented with a choice between doing something that is hard, time-consuming, complicated, or even inconvenient, and doing something else, my friend – and, in fairness, human beings generally seem to be – inclined to opt for the latter. Of course, the “hassle factor” CAN be trumped by exterior needs or forces, as anyone who has endured the long lines at the DMV or sat through the b...

Source "Spots"

Image
Individual retirement accounts (IRAs) have been around a long time – since the Employee Retirement Income Security Act of 1974 (ERISA), in fact[i]. Today IRAs represent nearly $6 trillion in assets, approximately a quarter of the $23.7 trillion in retirement plan assets in the nation. As an account type, they currently hold the largest single share of U.S. retirement plan assets with, as a recent EBRI publication notes, a substantial (and growing) portion of these IRA assets having originated in other tax-qualified retirement plans, such as defined benefit (pension) and 401(k) plans. Recognizing not only the significant growth but the increasing importance of these accounts to individual retirement security, the Department of Labor has proposed expanding ERISA’s fiduciary protections to these accounts. To help better understand the trends driving this critical retirement savings component, the EBRI IRA Database, an ongoing project that collects data from IRA plan administrators acr...

Pet "Smart"

Image
I’ve had both cats and dogs in my family over the years, and while each of our individual pets has had a unique personality, there are some attributes that seem to apply to each species, regardless of the individual animal. One of the most obvious is their approach to food.  For example, you can leave your cat alone in an apartment for a weekend with a supply of food and water sufficient to last for a few days, and odds are when you return home, there will still be some left.  But leave your dog alone in the same apartment with the same additional allotment of food and water, chances are it won’t last 30 minutes.  And in those circumstances, if you have both a cat and a dog in that apartment, odds are the latter will eat the former’s food as well. Animal psychologists have a variety of explanations for why dogs and cats approach food the way they do, generally citing either a confidence of its future availability, or a concern that if it’s not consumed now, it will disa...

Take It or Leave It?

Image
While each situation is different, in my experience leaving a job brings with it nearly as much paperwork as joining a new employer. Granted, you’re not asked to wade through a kit of enrollment materials, and the number of options are generally fewer, but you do have to make certain benefits-related decisions, including the determination of what to do with your retirement plan distribution(s). Unfortunately, even in the most amicable of partings, workers have traditionally lacked the particulars to facilitate a rollover to either an individual retirement account (IRA) or a subsequent employer’s retirement plan—and thus, the easiest thing to do was simply to request that distribution be paid to him or her in cash. Over the years, a number of changes have been made to discourage the “leakage” of retirement savings at job change: Legal thresholds for mandatory distributions have been set; a requirement established that distributions between $1,000 and $5,000 on which instructions a...

Connecting the Dots

Image
One of my favorite works of art is “A Sunday Afternoon on the Island of La Grande Jatte,” by Georges-Pierre Seurat. I was introduced to this painting in college via an art appreciation class at the Art Institute in Chicago (it even makes a brief appearance in the film “Ferris Bueller’s Day Off”). The subject matter isn’t really extraordinary―just a group of individuals scattered about a park taking in the scenery. But what amazed me the first time I got close to the painting―and does to this day―is that Seurat created these images, and the marvelous color shadings in these images, through the use of thousands (perhaps millions: the painting itself measures 7 by 10 ft.) of individual dots. Individual retirement accounts (IRAs) are a vital component of U.S. retirement savings, representing more than 25 percent of all retirement assets in the nation, with a substantial portion of these IRA assets originating in employment-based retirement plans, including defined benefit (pensio...

The Bigger Picture

Image
Over the weekend, my daughter shared with us an insurance quote she’d received.  It had been a while since I had focused on such things, but I was struck first by how much it was.  It was for insurance in a different state, so we worked through the particulars, trying to be certain that we understood what was covered, matched that against her needs.  Ultimately, while much of the quote made sense, there were a couple of items that seemed too high. As we probed those items, my daughter explained that the agent had made an effort to match those levels against her current coverage.  A logical enough inquiry and starting point, but one that (apparently) failed to take into account that her current coverage – as part of our family policy – would be quite different from what she needed on her own.  The agent got an accurate response to the question he asked – but it wasn’t the right question. Individual Retirement Accounts, or IRAs, hold more than 25 percent of a...

Balancing "Acts?"

Image
Last week we looked at how the trends in employment-based retirement plans and employment-based health plans seem to be heading in opposite directions: fewer choices for workers to make in the former, more in the latter (see Consumer “Driven,” online here.  Recent EBRI research suggests a potential divergence in other areas as well. According to the EBRI/MGA Consumer Engagement in Health Care Survey, 26–40 percent of respondents reported some type of access-to-health-care issue for either themselves or family members last year. “Access” in this case refers not to availability, per se, but is broadly defined as not filling prescriptions due to cost, skipping doses to make medication last longer, or delaying or avoiding getting health care due to cost. Not surprisingly, access is more of a problem among those with lower incomes, who appear to be forgoing spending on health care. In fact, regardless of health plan type, individuals in households with less than $50,000 in annual ...

“Drawing” Board?

Image
While drawing boards have been used by engineers and architects for more than two centuries, the phrase “back to the drawing board” is of much more recent origin, coined by the Peter Arno in a cartoon first published in the March 1, 1941 issue of New Yorker magazine.(1) The cartoon features a crashed plane in the background, a parachute in the distance, several military officials and rescue workers rushing to help/investigate—and one remarkably nonchalant individual, walking in the opposite direction with a rolled up document tucked under his arm as he comments, “Well, back to the old drawing board.” For all the much-deserved focus on retirement savings accumulations, a growing amount of attention is now directed to how those already in (and fast-approaching) retirement are actually investing and drawing down those savings. A recent EBRI analysis(2) found that at age 61, only 22.2 percent of households with an individual retirement account (IRA) took a withdrawal from that account...

“Like” Minded?

Image
Several weeks back, my wife and I sat down with a financial planner to review and update our financial plans. Doing so brought with it a bit of personal trepidation since, being “in the business” I not only had a working knowledge of what needed to be done, I also had a pretty good sense of what hadn’t been done, and what hadn’t been done the way it should have been done in some time. As I surrendered copies of the statements from my three separate 401(k) accounts, rollover IRA, traditional IRA, and SEP-IRA, I found myself wondering (again) why I hadn’t gotten around to consolidating some of those accounts. More and more Americans are finding themselves with multiple savings accounts, not only because of the relatively consistent pattern of job change in the American economy (see “Tenure, Tracked” ), but because those job changes frequently result in rollovers to individual retirement accounts. On the other hand, in recent years, it has gotten easier to simply leave your 401(k) with ...

Out of Cite?

Image
Our industry pays a lot of attention to the investment choices that retirement plan participants make; we fret about the type and number of choices on their investment menu, the efficacy of target-date funds, the utilization of active versus passive investment strategies, and the prudence of the asset allocation choices that individuals make—with or without the benefit of tools and/or professional guidance. Unfortunately, once they leave that part of our private retirement system, not so much. A significant percentage of that retirement plan money winds up in individual retirement accounts, or IRAs. In fact, today IRAs represent more than a quarter of all retirement assets in the U.S., according to a recent EBRI Issue Brief. But there remains a limited amount of knowledge about the investment behavior of individuals who own IRAs, alone or in combination with employment-based retirement plans. In order to fill this gap, EBRI has undertaken an initiative to study in depth this con...

Withdrawal “Symptoms”

Image
I was recently asked about the so-called 4 percent “rule.” That’s the rule of thumb(1) that many financial consultants rely on as a formula for how much money can be withdrawn from retirement savings every year (generally adjusted for inflation) without running out of money. Of course, like so many of the “assumptions” about retirement, certainly in the aftermath of the 2008 financial crisis, that withdrawal rule of thumb has drawn additional scrutiny.(2) At the time, my comment was that the 4 percent guideline is just that—a guideline. What’s not as clear is whether adhering to that guideline produces an income stream in retirement that will be enough to live on. How much are people actually withdrawing from their retirement accounts? At a recent EBRI policy forum,(3) Craig Copeland, senior research associate at the Employee Benefit Research Institute, explained that the median IRA individual withdrawal rates amounted to 5.5 percent of the account balance in 2010, thoug...