Posts

Showing posts with the label ERISA fiduciary

The ‘Fiduciary Rule’ that Wasn’t

Image
  After years of anticipation — and months of litigation — the Department of Labor’s latest attempt to expand the definition of fiduciary investment advice is now dead. That said, and with apologies to Mark Twain, reports of the “death” of the fiduciary rule are somewhat exaggerated. The 2024 version — the so-called Retirement Security Rule — was  vacated , which, in legal terms, means we treat it as if it never existed. But ERISA’s fiduciary framework remains very much alive. Indeed, for advisors already serving as fiduciaries for retirement plans under the Employee Retirement Income Security Act of 1974, the practical impact of the recent court ruling is minimal. Advisors serving as 3(21) fiduciaries or 3(38) investment managers were — and remain — subject to ERISA’s duties of prudence and loyalty.  Many advisory firms, frankly, had already adopted procedures and business models that would likely have satisfied even the Obama-era fiduciary rule. Where the rule...

The Founding Fathers and Fiduciary Fundamentals

Image
Anyone who has ever found their grand idea shackled to the deliberations of a committee, or who has had to kowtow to the sensibilities of a recalcitrant compliance department, can empathize with the process that produced the Declaration of Independence we commemorate this week. Not that the machinations of a plan committee can be fairly equated to the deliberations—or impact—of the Second Continental Congress, but there are some parallels. Things like… Committee members should understand their obligations—and the risks. Those who gathered in Philadelphia that summer of 1776 came from all walks of life, but it seems fair to say that most had something to lose. True, many were merchants (some wealthy, including President of Congress John Hancock) already chafing under the tax burdens imposed by British rule, and perhaps they could see a day when their actions would (eventually) accrue to their economic benefit. Still, they could hardly have undertaken that declaration of ...

The 'Best' of 2022

Image
 I’ve been writing a weekly column (and then some) for more than two decades now. Some are easier to write (and read)—and some hold up better (and longer) than others. These are some of my (and perhaps your) favorites from 2022. Let me know what you think in the comments below… particularly if I have missed one of your favorites…   7 Things to Know About the New ESG Regulation There’s a lot to unpack in that regulation (and the rest of the 236-pages that help explain its process and rationale), but here’s a few things that seem particularly important to note at the outset. https://www.napa-net.org/news-info/daily-news/7-things-know-about-new-esg-regulation ‘Damned’ (Even) If You Do The flurry of lawsuits unleashed on holders of the BlackRock LifePath target-date funds is not without precedent—but it’s surely a head scratcher. https://www.napa-net.org/news-info/daily-news/damned-even-if-you-do Things to Ponder In the course of my day, I talk t...

5 Dangerous Fiduciary Assumptions

Image
There’s an old saying that when you assume… well, here are some assumptions that can create real headaches for retirement plan fiduciaries. Assuming that the worst-case deadline for depositing participant contributions IS the deadline for depositing participant contributions. The legal requirements for depositing contributions to the plan are perhaps the most widely misunderstood elements of plan administration. A delay in contribution deposits is also one of the most common signs that an employer is in financial trouble—and that the Labor Department is likely to investigate. Note that the law requires that participant contributions be deposited in the plan as soon as it is reasonably possible to segregate them from the company’s assets, but no later than the 15th business day of the month following the payday. If employers can reasonably make the deposits sooner, they need to do so. Many have read the worst-case situation (the 15th business day of the month following...

‘Damned’ (Even) If You Do

Image
The flurry of lawsuits unleashed on holders of the BlackRock LifePath target-date funds is not without precedent—but it’s surely a head scratcher. I’m referring, of course, to the recent  swarm of lawsuits  challenging nearly a dozen of the nation’s largest 401(k) plans and their decision(s) to select, and hold, on their investment menu the BlackRock LifePath target-date fund suite. It’s a decision that the Shah Miller law firm (on behalf of multiple ex-participant plaintiffs) says was the result of fiduciaries who “chased low fees” over performance. [i] Of course, it’s not unusual for these types of lawsuits cite obscure articles as authority, rely on Form 5500 data that often doesn’t tell the whole story, state as fact things that are really only theories (or opinions), lean on averages, or base comparative conclusions on surveys distorted by sampling size or content.  But in a characterization straight out of George Orwell’s  1984 , this one draws...

Are We Ready for Retirement Income?

Image
It’s ironic that programs designed to provide retirement income pay so little attention to the realization of that objective. That’s right—for the vast majority of participants today, creating that “paycheck for the rest of your life” remains a DIY undertaking. To this day only about half of defined contribution plans currently provide an option for participants to establish a systematic series of periodic payments, much less an annuity or other in-plan retirement income option.  However, the need for that solution is widely acknowledged—and there are some new, if somewhat familiar, solutions emerging.  Earlier this month, BlackRock garnered some  headlines  with news that not only was it building annuity contracts into a target-date fund series, but also that it had already lined up five large plan sponsors (with some $7.5 billion in assets) to implement the option as a default. That followed by a few months the March  announcement  of a c...

5 Plan Committee Missteps

Image
There is frequently a difference between doing what the law requires and doing everything that you could do as a plan fiduciary. That said, there are things that plan fiduciaries must do—and things that, while not required, can keep the plan, and plan fiduciaries out of trouble. Let’s get started. 1. Not having a plan/plan investment committee ERISA only requires that the named fiduciary (and there must be one of those) make decisions regarding the plan that are in the best interests of plan participants and beneficiaries, and that are the types of decisions that a prudent expert would make about such matters. ERISA does not require that you make those decisions by yourself—and, in fact, requires that, if you lack the requisite expertise, you enlist the support of those who do have it.  You may well possess the requisite expertise to make those decisions—and then again, you may not. But even if you do, why forego the assistance of other perspectives? However, h...

Limiting Fiduciary Liability (Costs)

Image
 A recent survey of insurers highlights the criteria that a number of the nation’s leading fiduciary liability insurers identified as the biggest sources of fiduciary risk—within the control of plan fiduciaries.  Now, arguably, the report—titled “ What Drives Fiduciary Liability? ”—might have been more accurately titled “What Drives Fiduciary Liability Insurance Costs?”—or even more precisely “What Drives Fiduciary Liability Insurance Costs That You Can Do Something About?” Indeed, the report’s authors note that it was specifically focused on sources of risk that are within the control of fiduciaries. That’s key, because there  are  things that attract litigation (such as plan size or even stock price) that aren’t.  Moreover, the survey respondents (there were 8 of the 12 that Aon said account for 85% of the total gross written premium placed by the firms in 2020) were asked only to evaluate pricing criteria as having a significant, small or nonex...

History’s Lessons for Plan Fiduciaries

Image
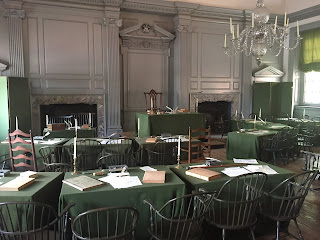
The study of history is a passion of mine, and while it seems a bit trite, the old adage that those who don’t remember the past are doomed to repeat it seems more apropos by the day. Regardless, I never cease to be touched by the experience of walking the grounds where famous individuals or great historic events took place.  A few years back I had the opportunity to be in Philadelphia for a few days beyond the customary speaking event “fly-by,” and was thrilled to be able to tour Independence Hall where, in 1776, the Continental Congress crafted what we will shortly celebrate as the Declaration of Independence. Those who think that partisan divides, cynical self-interest, and political acrimony are recent “innovations” in government would perhaps be shocked to learn that regional tensions have always been part-and-parcel of our republic… even before it was a republic.  The room was smaller than I had imagined—and I couldn’t imagine what it must have felt like o...

"Missing" Inaction?

Image
Recent DOL guidance on missing participants seems to fall short of what plan fiduciaries want/need—but may offer fiduciaries some key insights to avoid future problems. On Jan. 12, 2021, the Department of Labor (DOL) released a triple dose of guidance  related to helping retirement plan fiduciaries meet their obligations under the Employee Retirement Income Security Act (ERISA) to distribute retirement benefits to missing participants. Arguably the guidance, while welcome, is less than plan sponsors might have wished (and previously asked ) for—and it concerns an issue that most plan sponsors of my acquaintance continue to insist isn’t one, though the Labor Department is clearly of a different mind. In fact, in the first of the three pieces of guidance, the Employee Benefit Security Administration (EBSA) cautions: “The first step in addressing any problem often is knowing that there is one.” [i] The “issue,” of course, is fulfilling the fiduciary obligation to ...

How Much (Should) a New Committee Member Know?

Image
A recent federal court decision should remind us all of the importance of plan committee education. The case involved a suit by participants in the SunTrust 401(k) plan (see Is Fiduciary Responsibility Retroactive? ) that challenged the initial selection of, and subsequent acquiescence with, an ostensibly imprudent plan investment menu. The court’s decision focused on one aspect of the case: the liability of “new” plan committee members for actions that predated their involvement on the committee, but continued after their involvement. The court, in a decision that will likely be viewed favorably by new committee members, excluded them from liability for committee moves that predated their participation, at least to the extent they lack “actual knowledge” of imprudence. Along the way to that determination, Judge Orinda D. Evans of the U.S. District Court for the Northern District of Georgia incorporated the testimony of those new committee members as to t...

5 Fiduciary Fundamentals: A Founding Fathers Perspective

Image
This week we’ll commemorate Independence Day – but with all of freedom’s lessons, there are certain things that plan committees (still) have in common with the Second Continental Congress. Certainly anyone who has ever found their grand idea shackled to the deliberations of a committee, or who has had to kowtow to the sensibilities of a recalcitrant compliance department, can empathize with the process that produced the Declaration of Independence we commemorate this week. Consider these similarities: Committee members should understand their obligations – and the risks. Those that gathered in Philadelphia that summer of 1776 came from all walks of life, but it seems fair to say that most had something to lose. True, many were merchants (some wealthy, including President of Congress John Hancock) already chafing under the tax burdens imposed by British rule, and perhaps they could see a day when their actions would (eventually) accrue to their economic be...