Posts

The Contingency 'Plan'
Image
So, how much should the plaintiffs’ attorneys who wrangled a $12 million settlement receive for their time, effort and trouble? Well, if you’ve been keeping up with such things, you’ll do some quick math and arrive at a figure of $4 million since, after all, these class action suits [i] —undertaken on a contingent fee basis—generally produce a pay day of somewhere between 25% and 30% of the settlement amount. [ii] In this case, that’s the settlement amount requested by the law firm of Schlichter Bogard & Denton for their work in a suit involving Oracle Corp. and its 401(k) plan (over 6,300 hours—5,631.10 hours of attorney time & 696.5 hours of non-attorney time—according to the filing ( Troudt v. Oracle Corp . , D. Colo., No. 1:16-cv-00175, motion for attorneys’ fees 5/8/20). That’s aside from the requested reimbursement of what those same attorneys characterize as “reasonable out-of-pocket expenses of $410,501.60, [iii]  and $25,000 for each of the named clas...
A Bad Example

Image
You have to hand it to the  Washington Post . At a time when millions of working Americans are finding a financial lifeline in their retirement savings, they managed to find in the questionable life choices of a half dozen individuals a condemnation of the nation’s private retirement system. The piece, laboriously titled “ Millions of baby boomers are getting caught in the country’s broken retirement system ” is light (and selective) on data (they managed to get hold of a 2016 report by the Economic Policy Institute subtitled “How 401(k)s have failed most American workers,” some datapoints from the National Institute on Retirement Security (for those who have forgotten some of the issues with their database, see Data ‘Minding’ ” and a couple of quotes from none other than Teresa Ghilarducci). Indeed, the article isn’t really about factual data; rather it’s mostly reliant on the anecdotes of six individuals the author has somehow stumbled upon. Weirdl...

The Next Chapter

Image
Life has many lessons to teach us, some more painful than others—and some we’d just as soon be spared. But for the graduates of 2020—well, theirs is surely a unique time. So, if you have a graduate—or if you ARE a graduate, here are some thoughts…    My kids have passed those milestones—but I have two nieces that will graduate this year without an “official” ceremony to commemorate the occasion, no capstone to those years in pursuit of education, and preparation for the next of life’s stages, and—while social media, cell phones, TikTok and Zoom provide some solace—this is a class that will, for the moment anyway, be denied the hugs and warm embraces of classmates, friends and family alike. That said, those next steps lie ahead—and if the when, where (and how) remains elusive—the if is surely only a matter of time. And as graduates everywhere look ahead to the next chapter in their lives, it seems a good time to reflect on some lessons learned along the way—m...

Corona Conscious

Image
Perhaps like many of you, I spent the last week watching a series of announcements regarding various school and business closings associated with the coronavirus—but I was also keeping an eye on my retirement savings. I know—this is exactly the thing that most advisors counsel against, not only because it might be depressing (though there’s been plenty of inspiring moments), but because human beings are often inclined to react emotionally, not rationally in markets like these. And, seriously, have there  ever   been markets like these? Now many, perhaps most, participants and plan sponsors will embrace the counsel to not only avoid taking action, but to avoid paying any attention to the short-term volatility of what is, by its very nature, a long-term investment. That said, some will undoubtedly want to do  something. And for those, I offer the following alternatives. If you’re in a target-date fund or managed account: Leave it alone....

'Nothing' Doing

Image
If you’ve been asked in the past two weeks what to do about the market (and who hasn’t), I’m sure your response has been something along the lines of . . . “Nothing.” There are, of course, more eloquent ways to express that sentiment. And, let’s face it, when it seems that everyone is asking that question—it’s generally well past the time when it is prudent to try and do—well, anything. Still, it seems that throughout my professional career, every time the market plunges (even when it stays down for an extended period), the pundits all seem to say the same thing; “the fundamentals are sound,” “we’re going through a period of short-term volatility,” or “we were due for a correction” (sometimes all of the above). Granted, this period seems unusual—there is a non-financial cause (the coronavirus outbreak) that is projected/anticipated to have a financial impact of unknown size and duration. That it has emerged at the outset of what is likely to be one of the more conten...

Disclose 'Sure'

Image
There are few things more annoying in my daily existence than those ubiquitous pop-up service agreement acknowledgements. I say annoying because they are inevitably long and “lawyerly”; there’s no way that they can readily be read (much less absorbed) in the medium in which they are presented; and the alternative to not accepting the conditions presented would seem to be to forego the update that you’ve been encouraged to accept, and that, at some point in the future would seem to have its own dire consequences. And so, probably like many, if not most, if not all, of you, means that I accept the terms, and acknowledge the disclaimers basically sight unseen (or at least unread). Last week  the U.S. Supreme Court weighed in on a case involving participant disclosures, specifically the issue of whether certain plan disclosures were sufficient to establish a participant’s “actual knowledge” of the design of Intel’s custom target-date series, which had been built incl...

'Tacts' Treatment

Image
Roth 401(k)s are more prevalent—and popular—than ever. But is that good—or bad—for retirement? A recent op-ed [i]  in  The Wall Street Journal  explored the potential implications— “What ‘Rothifying’ 401(k)s Would Mean for Retirees” — (subscription required), though the focus is on tax policy as well. You’ll remember that so-called “Rothification”—essentially the elimination of the pre-tax treatment currently accorded 401(k) contributions—was quite the controversial issue back in 2017 when the Republican-controlled House of Representatives was looking for ways to raise revenue to help pay for tax cuts. [ii]  And while it’s not been an active focus of late, it seems likely to resurface as the nation’s budget deficit widens, and the field of 2020 presidential aspirants seem determined to find ways to spend more or, in the case of the incumbent, collect less in taxes. ‘Out’ Comes  As for the WSJ treatment, I’ll spare you the short read (longer ...

After the Fall

Image
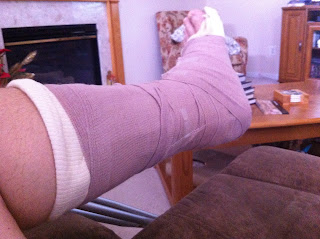
I’ve just passed the fifth anniversary of a small fall that took a big chunk out of my life. It was one of those little things – carrying that last box of Christmas ornaments to the basement for storage – when, just three steps from the bottom, I missed one. All I could think about in the 2 seconds it took me to tumble to the ground was trying not to fall on the ornaments (it was the last box, but who knew what precious memories were in that one?) – though that focus completely disappeared once I hit the floor. The ornaments, as it turned out, were safe. My left ankle, not so much. The next several weeks were discouragingly inconvenient when it came to navigating stairs, opening doors (even the ones that are ostensibly designed to accommodate such things), and – worst of all – showering. But perhaps the most frustrating was my rehab stint. I would not have thought it was possible in the space of just 8 weeks to forget how to walk – and yet, I found myself struggl...

The End in Mind

Image
Could lifetime income disclosures undermine retirement savings? Over the past several years, a growing amount of attention has been focused on the decumulations of defined contribution plan balances in retirement – and a sense that the emphasis on account growth, and account balances, glosses over the reality that at some point in the future those savings will need to be turned into a retirement paycheck. Enter the SECURE Act, which among its numerous retirement-related provisions added the new “lifetime income disclosure” requirements  to ERISA’s benefit statement rules. It applies to individual account plan benefit statements and the lifetime income disclosure must be provided in one benefit statement during each 12-month period. Simply stated, the new law requires that the participant’s total accrued benefit be expressed as a “lifetime income stream” in the form of a single life annuity and a qualified joint and survivor annuity, assuming the participant has a ...

Question Err?

Image
“Presumably, if workers earned income in a retirement account, it is safe to assume that they had a retirement account…”. Ya think? That somewhat self-evident statement is drawn from a recent Issue Brief  by the non-partisan Employee Benefit Institute (EBRI). That it was necessary is a cautionary tale about the blind reliance on data, even from a credible source, that looks suspicious. It relates to the Current Population Survey (CPS), Annual Social and Economic Supplement (fielded in March of each year) to the CPS, conducted by the U.S. Census Bureau – a report that had long been one of the most cited sources [i]  of income data for those whose ages are associated with being retired. ‘Bold’ Move The problem appears to have its roots in a well-intentioned attempt to provide a more accurate read on income from DC plans. Responding to research that indicated that the CPS misclassified and generally underreported income, particularly pension income, th...

Could the Super Bowl’s Outcome Kick Your 401(k)?

Image
Will your portfolio be fortified by a 49ers win – or get chipped by the Chiefs? That’s what adherents of the so-called Super Bowl Theory would likely conclude. The Super Bowl Theory holds that when a team from the old National Football League wins the Super Bowl, the S&P 500 will rise, and when a team from the old American Football League prevails, stock prices will fall. It’s a “theory” that has been found to be correct nearly 80% of the time – for 40 of the 53 Super Bowls, in fact. Not that it hasn’t had its shortcomings. One need look back no further than last year’s win by the AFC’s New England Patriots over the NFC champion Los Angeles Rams to find an exception – the S&P 500 was up more than 30% in 2019. And then it was just the year before that a win by the NFC champion Philadelphia Eagles against the AFC Champion Patriots (who once were the AFL’s Boston Patriots) also turned out to be a loser, marketwise, with the S&P 500 down more than 6% (though...

The 'Cutting' Edge?

Image
Are employers necessary for a successful retirement system? A new proposal suggests that their role be “jettisoned.” Not one to simply “bash” the 401(k), and to his credit, Morningstar’s John Rekenthaler, who recently opined  that the 401(k) had outlived its usefulness, [i]  now offers an alternative that he considers to be a superior alternative, something he titles “the New American Retirement Plan.” Despite the shortfalls his previous column attributed to the 401(k), this proposal  in most of its elements seems relatively modest, at least structurally. It’s (basically – in 25 words or less), a national DC plan for all employers, probably with mandatory employee contributions, no requirement for employer contributions, and tighter restrictions on withdrawals. [ii] Make no mistake, though – the devil, and there’s mischief aplenty here – lies in the details. Rekenthaler’s basic premise – one that he describes not only as “the first,” but the “most impor...

Has the 401(k) Passed its ‘Expiration Date’?

Image
That’s the premise behind a recent column by Morningstar’s John Rekenthaler, who writes that “the plans are as good as they can be under the current framework – and that's not good enough.” I had the pleasure of meeting John a number of years back – and I’ve been keeping up with his writing ever since. His columns are thoughtful and thought-provoking, his perspectives rational and well-reasoned, his commentary nearly always not only interesting, but entertaining. But on this one  – well, let’s just say we disagree. John acknowledges that his views on the 401(k) have “evolved,” and that while he has long been in the camp that called for improvements in the current system, a “defender” of the 401(k) – but now, apparently, he’s calling for an “overhaul.” ‘Leaky’ Assumptions He doesn’t fault the current system for its perceived shortcomings; he notes that the 401(k) wasn’t designed to be a solution for the general public’s retirement, saw the growth in the 1980s...

‘Still’ Standing: 6 Key Industry Trends to Watch

Image
The Plan Sponsor Council of America recently released its 62nd   Annual Survey of Profit-Sharing and 401(k) Plans ,  documenting a record high rate of savings, alongside an uptick in Roth contributions and other trends. However, sometimes the things that  don’t  change can be just as telling… Target-date trends (still) dominate, but…  Let’s face it – target-date funds are one of the most common items on a plan investment menu today ( the PSCA survey  noted that it’s the option in which assets are most frequently invested) and – in no small part due to their prevalence as a default investment alternative – continue to garner a lion’s share of new contribution dollars, if older savers (perhaps more precisely, longer-tenured savers) haven’t embraced (or more accurately, been defaulted into) the option with as much enthusiasm. That said, while more than two-thirds (68.6%) of respondents offer a target-date fund option, that’s actually down 5% in ...